What Is NIN Verification, and How Does It Work Today?
If you've ever been asked to provide your NIN when signing up for a financial service, you may have wondered what actually happens after you enter those numbers.
NIN verification is simply the process of confirming that a National Identification Number belongs to the person presenting it. The verification is done against records maintained by the National Identity Management Commission (NIMC).
Think of it as one of the building blocks behind the identity checks we've discussed in our KYC and KYB guides. BVN helps confirm someone's identity within the banking system, while NIN provides a broader national identity record. But there's an important detail that many older articles about NIN verification miss.
The way NIN verification works has changed.
NIMC introduced the Virtual NIN, or vNIN, to provide a safer way for people to share their identity information without handing over their actual eleven digit NIN.
Instead of giving a business your permanent NIN, you can generate a temporary, tokenized version of it through the NIMC MobileID app. This vNIN is a sixteen character token that represents your NIN without exposing the original number.
The business uses the vNIN to perform the verification against NIMC's system. Once the token's validity period expires, it cannot simply be reused. That difference is important.
If a temporary verification token is intercepted, its usefulness is limited. A raw NIN, on the other hand, is a permanent identifier.
For businesses collecting identity information at scale, that distinction matters.
How NIN Verification Actually Works
NIN verification isn't necessarily one single type of check. NIMC's Verification Service API supports several verification methods, depending on how much confidence the business needs. A business can verify using the NIN alone. It can also combine the NIN with fingerprint information, use demographic information, or perform an identity search using fingerprint or demographic data. So there is a difference between simply asking:
"Is this NIN valid?" and asking:
"Does this NIN actually belong to this person?" The second question may require additional information such as biometric or demographic verification. That distinction becomes particularly important for fintechs, lenders and other businesses making decisions where identity confidence matters.
How vNIN Verification Works: Step by Step
So what actually happens when a customer uses vNIN? Let's walk through it in simple terms.
1. The customer generates a vNIN
The customer opens the NIMC MobileID app on their phone, logs in using their PIN and selects "Get Virtual NIN." The app generates a sixteen character token connected to the customer's identity. The important part is that the customer's actual NIN isn't being handed directly to the business.
2. The customer gives the vNIN to the business
The business, known in NIMC's terminology as the "Relying Party," asks the customer to provide the vNIN after obtaining the necessary consent. Depending on how the business has implemented the process, the customer may type the vNIN, provide it verbally, or share it through a QR code generated by the app.
From the customer's perspective, this is simply another step in the onboarding process.
Behind the scenes, however, it is helping keep the underlying NIN from being unnecessarily exposed.
3. The vNIN has a limited validity period
This is one of the most important things to understand about vNIN. It isn't permanent. A vNIN has a defined period during which it can be used for verification. That is intentional. If the token somehow ends up in the wrong hands, it doesn't remain useful indefinitely. Once it expires, it cannot simply be reused for another verification.
4. NIMC performs the verification
Once the business submits the vNIN, the request is checked against NIMC's records. The business doesn't simply get direct access to NIMC's underlying database. Instead, the verification process returns a result that the business can use. That result could then help the business decide whether to approve the customer, continue onboarding, move the customer to another verification level, or request additional information.
5. The business makes a decision
This is where verification becomes more than just a technical exercise. A verification result is ultimately used to support a business decision. For example, a fintech might use it to determine whether a customer can complete registration. A lender might use additional verification when a higher level of confidence is required.
The principle is similar to what we discussed in our KYB guide: Not every customer needs the same level of scrutiny. The level of verification should depend on the risk and the purpose of the transaction.
Why vNIN Matters for Businesses
There is a bigger reason behind this shift that businesses shouldn't overlook. Traditional identity verification often meant collecting and storing sensitive identity information.
That creates a problem. The more sensitive information your business stores, the more information there is to protect.
The vNIN model provides another approach. Instead of routinely collecting the customer's permanent NIN, the business can use a temporary token for verification. That's particularly relevant for fintechs and other businesses thinking about data protection, privacy and their obligations under Nigeria's data protection framework.
In simple terms: A permanent identifier creates a permanent data protection responsibility. A temporary verification token can reduce the amount of sensitive identity information unnecessarily exposed during the verification process.
NIN vs BVN: What's the Difference?
This is one of the most common areas of confusion. People often talk about NIN and BVN as though they're interchangeable. They're not. They were created for different purposes and come from different systems. BVN is primarily a banking identity. It connects an individual to their banking relationships and helps financial institutions recognize the same person across the banking system. NIN is a broader national identity. It is issued by NIMC and is used beyond banking, including areas such as SIM registration and various government and digital services. So while both can help answer the question "Who is this person?", they approach the problem from different perspectives. BVN helps establish someone's identity within the financial system. NIN provides a broader national identity record. And that's why businesses shouldn't necessarily think of them as competitors. In many cases, they work better together.
Why Fintechs May Need Both NIN and BVN
Consider a digital lender onboarding a new customer.
A BVN check can provide useful information about the customer's established identity within the banking system.
But that doesn't necessarily give the business the complete identity picture that NIN can provide through national demographic and biometric records. That's one reason higher KYC tiers can require stronger identity verification rather than relying on a single identifier.
The practical challenge, however, is onboarding friction. BVN verification can often feel almost invisible to the customer because it is deeply integrated into financial services.
NIN verification, particularly when using vNIN, can introduce an additional step because the customer may need to actively generate the virtual NIN through the MobileID app.
That's not necessarily a bad thing. But it does need to be designed properly. If a customer is asked for BVN, NIN, a document, a selfie and several other pieces of information without understanding why, the onboarding experience can quickly become frustrating. The better approach is to make each verification step purposeful. Explain what you're checking. Explain why you're checking it. And, where possible, make the process fast enough that the customer barely notices the security happening in the background.
NIN or BVN: Which One Should Your Business Use?
There isn't a universal answer. It depends on what your business does, the level of risk you're managing and the level of verification your customers require. A simple way to think about it is: BVN: "Does this person have an established identity within the Nigerian banking system?" NIN: "Can this person's identity be verified against Nigeria's national identity records?" Both: "Can we build a stronger picture of who this customer is using multiple trusted identity signals?" For a fintech, lender or other regulated business, the question shouldn't simply be "NIN or BVN?" The better question is: "What level of identity confidence does this customer and this transaction require?" That's where good KYC design starts. And ultimately, NIN verification isn't just another box to tick during onboarding. When implemented properly, it's part of a bigger goal: making sure the person on the other side of the screen is genuinely who they claim to be, while keeping the experience simple enough for legitimate customers to move forward.
Verifying NIN Through an API
So far, we've looked at what NIN verification is and how the process works from the customer's perspective. But if you're actually building a fintech product, lending platform, marketplace, or digital service, there's another question that matters: How do you connect NIN verification to your product without building the entire infrastructure yourself?
That's where APIs come in.
How NIN verification works through an API
One important thing to understand first is that NIN verification isn't an open API that any business can simply sign up for and start calling. Businesses that want to integrate directly with NIMC need the appropriate Enterprise ID and RP short code issued by NIMC. The connection also operates through a secured channel, rather than simply exposing the verification service through an ordinary public internet endpoint. Every request is tied to the organization making it, so NIMC can identify who is requesting the information and why.
Once the appropriate access is in place, the verification service supports several methods. Depending on the use case, a business can verify using a NIN or vNIN, combine the check with fingerprint information, use demographic information, or perform an identity search using biometric or demographic data. This gives businesses some flexibility.
A simple NIN or vNIN check may be enough for a lower risk use case. A business dealing with higher risk transactions may need additional information to establish greater confidence in the customer's identity.
The vNIN process also fits into this API infrastructure. The business submits the customer's vNIN along with the required credentials, NIMC performs the verification, and the business receives the relevant verification result.
What about NINAuth?
There's another development worth paying attention to: NINAuth. NINAuth is a broader identity authentication platform being rolled out by NIMC. It is designed to provide a more centralized way of authenticating identity across different services and government agencies. The important idea here is consent.
Rather than businesses simply requesting someone's identity information in the background, the system is designed around the individual authorizing access to their identity data.
For fintechs and other businesses building digital onboarding systems, this points toward a bigger shift in Nigeria's identity infrastructure. Instead of having several disconnected identity checks doing different things, the direction appears to be toward a more connected government-backed identity authentication layer.
Should you integrate directly with NIMC or use a verification provider? For a business, there are essentially two approaches. The first is to integrate directly with NIMC. That gives you more direct control, but it also means your technical team has to handle the Enterprise credentials, secure connectivity, NIMC's technical requirements, ongoing maintenance, and the compliance responsibilities that come with the integration.
The second option is to work with a licensed verification provider that already has the relevant integration and exposes the functionality through an API that your product can consume.
For many businesses, this can be considerably more practical. It's similar to the way companies approach CAC and KYB verification. Instead of building an entire government data integration infrastructure internally, they use a specialist provider that handles the complexity behind the scenes. There's also another consideration that is easy to overlook.
Nigeria's identity verification infrastructure is evolving. The move toward vNIN and the emergence of NINAuth show that the way identity verification works today may not necessarily be the way it works a few years from now.
So when you're evaluating a verification provider, don't only ask: "Can you verify NIN?" Ask a more important question: "How directly are you connected to the source, and how quickly can you adapt when the source changes?" That distinction can have a major impact on reliability, especially for a business whose onboarding process depends heavily on identity verification.
How Lumiid Verifies NIN Through an API
If you're a business that simply wants to add NIN verification to your product, you shouldn't have to build all of that infrastructure yourself. This is where Lumiid comes in. The process is designed to be straightforward. A user provides their NIN during your existing registration or onboarding process.
Your application sends the NIN to the Lumiid verification API using your API credentials.
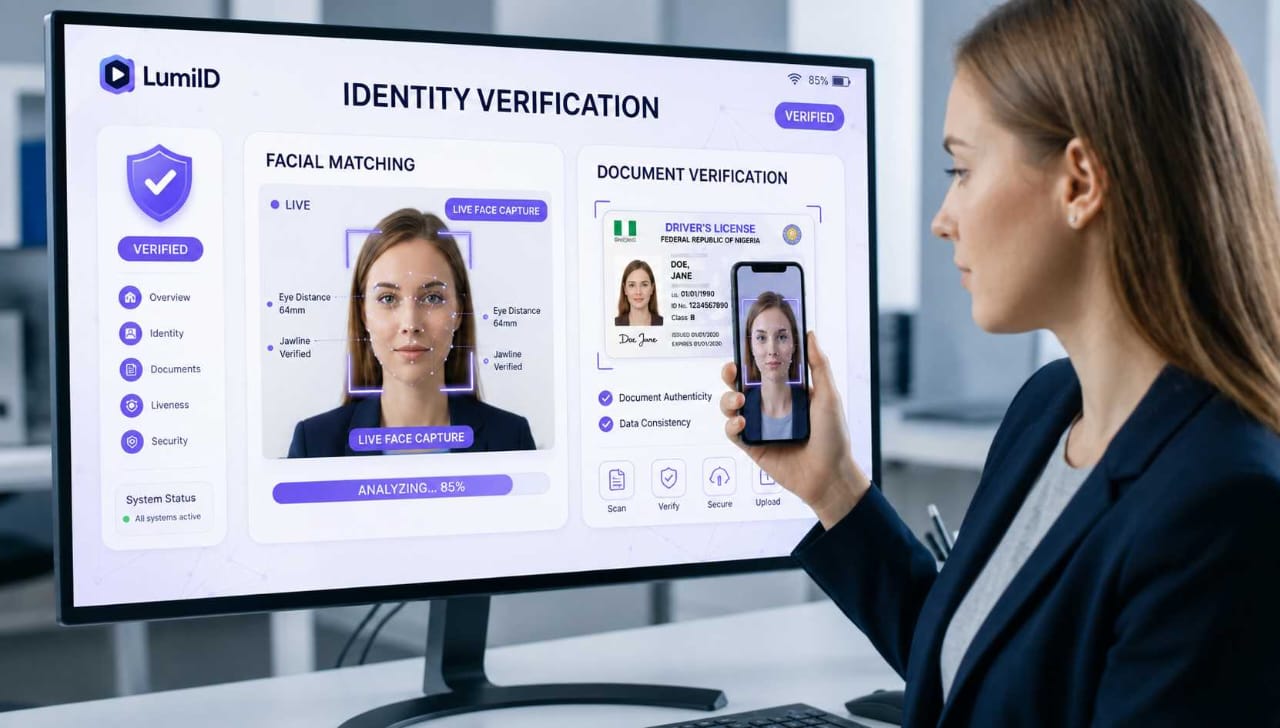
Lumiid processes the verification against the available identity data source and returns the verification result to your application. Your application can then use that result to decide what happens next. For example, you might approve the account, assign a risk level, continue with another KYC check, or request additional verification where necessary. In simple terms:
User provides NIN → Your application sends it to Lumiid → Lumiid verifies it → Result comes back to your application. That's the advantage of using an API-based verification provider. Your development team doesn't have to build the entire NIMC integration from scratch, manage the underlying connectivity, or maintain the government integration themselves. You focus on building your product. The verification infrastructure handles the identity check behind the scenes.
What happens to the NIN after verification?
This is an important question, especially for businesses thinking seriously about data protection and compliance. Lumiid retains the NIN provided during verification rather than automatically discarding it immediately after the check. That's intentional. For businesses operating under KYC and regulatory requirements, verified identity information may need to be retained for a defined period to support compliance, auditing, and the ongoing business relationship. That doesn't mean the information should be kept forever. The principle is simple:
Keep what you legitimately need, protect it properly, and don't retain it longer than necessary.
Lumiid's approach is therefore not based on pretending that NIN data never needs to be stored. It's about taking responsibility for securely handling that information when it does need to be retained. The data is encrypted at rest and retained according to the applicable business and compliance requirements. For a fintech, that means you don't have to build the entire infrastructure for securely storing and managing verified identity information yourself.
Frequently Asked Questions
Is NIN verification required to open a bank account in Nigeria?
For many account tiers, NIN verification forms part of the identity requirements alongside BVN.
The exact requirement depends on the account type and applicable regulatory framework.
For businesses building onboarding systems, the important point is that NIN and BVN increasingly form part of the identity information financial institutions need to manage effectively.
What is a Virtual NIN?
A Virtual NIN, or vNIN, is a tokenized version of a person's NIN. Instead of sharing the underlying eleven digit NIN directly, the customer generates a temporary sixteen character token that can be used for verification. The idea is to reduce unnecessary exposure of the customer's permanent NIN.
Can NIN be verified without a smartphone?
Yes. The vNIN process is not limited exclusively to smartphone users. USSD-based options are also available, although the mobile application can provide a more convenient experience for many customers. For businesses, this is important because onboarding shouldn't automatically exclude customers simply because they don't have access to a particular device or application.
How long does NIN verification take?
The verification itself is designed to happen in real time. In many cases, the part that takes longer isn't the actual verification request. It's the customer's interaction with the process, such as generating and providing their vNIN.
For a business, this distinction matters. A verification system can technically be fast, but the overall customer experience can still feel slow if the onboarding flow isn't designed properly.
What's the difference between NIN verification and NINAuth?
Think of NIN verification as the identity check and NINAuth as the broader authentication platform. NIN verification confirms whether the submitted NIN or vNIN corresponds with the relevant identity record. NINAuth is designed as a broader identity authentication framework that can support identity verification across different services. They're related, but they're not exactly the same thing.
Should a business integrate directly with NIMC or use a verification provider?
Both approaches are possible.
Direct integration gives a business more control but comes with additional technical, connectivity, maintenance, and compliance responsibilities. Using a licensed verification provider allows the business to access identity verification through an existing integration.
For many startups and growing businesses, that can be the more practical option because the development team can focus on the product rather than maintaining an entire government identity integration.
The Bigger Picture
NIN verification in Nigeria is changing. The old mental model was fairly simple:
Give us your NIN. We'll check it. The newer model is much more focused on security, consent, and reducing unnecessary exposure of permanent identity information.
That's where vNIN becomes particularly important.
Instead of repeatedly handing out a permanent eleven digit identifier, customers can use a temporary token designed specifically for verification. And with NINAuth emerging as a broader identity authentication infrastructure, the direction of travel is becoming even clearer.
For businesses, this isn't just a technical change. It's a reminder that identity verification is becoming an important part of the infrastructure behind digital businesses in Nigeria. If you're building a fintech, lending platform, marketplace, HR platform, or any digital product that needs to establish who your customers are, the question isn't simply:
"Can we verify NIN?"
It's:
"Can we verify identity quickly, securely, and in a way that creates a good customer experience?"
That's the problem Lumiid is built to help businesses solve. With Lumiid, businesses can integrate NIN verification into their existing onboarding workflow through an API, without having to build and maintain the entire verification infrastructure themselves.
Build faster. Verify with confidence. Protect the trust you've worked to earn.